The annual output of titanium materials in my country is about 50,000 tons, and the total sales volume is about 44,000 tons, of which 36,000 tons are sold domestically. In my country, titanium processing materials are mainly used in the chemical industry, followed by aerospace, electric power, etc. In my country, about 42% of titanium materials are used in traditional chemical fields, and titanium materials used in aerospace account for less than 20%, far below the international average of about 50%. At present, titanium used in global aerospace accounts for about half of the total titanium materials, and the demand for aviation titanium materials in the United States, Russia and other countries accounts for even more than 70%. At present, the global aviation titanium alloy market scale is about 30 billion/RMB. The titanium alloy market size is about 10 billion.
|
|
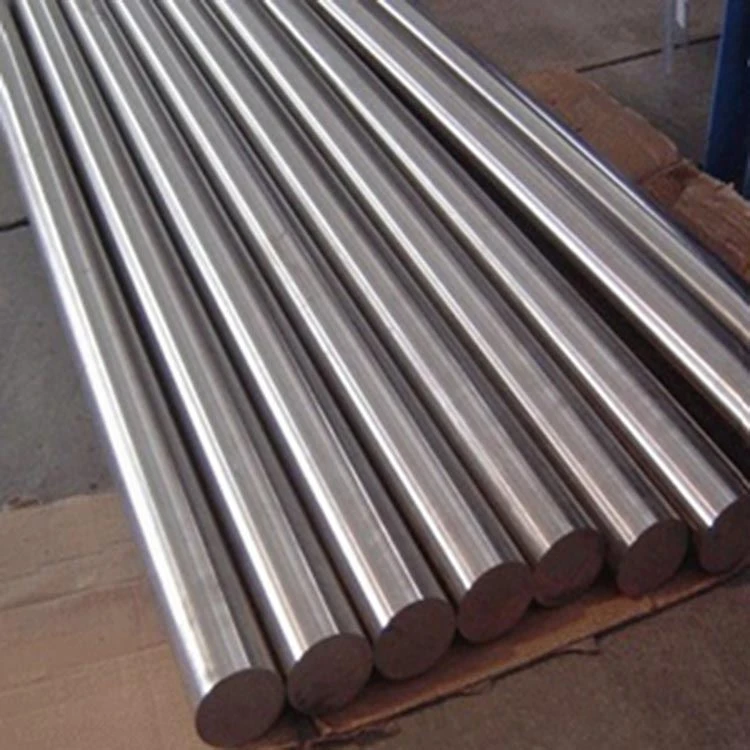
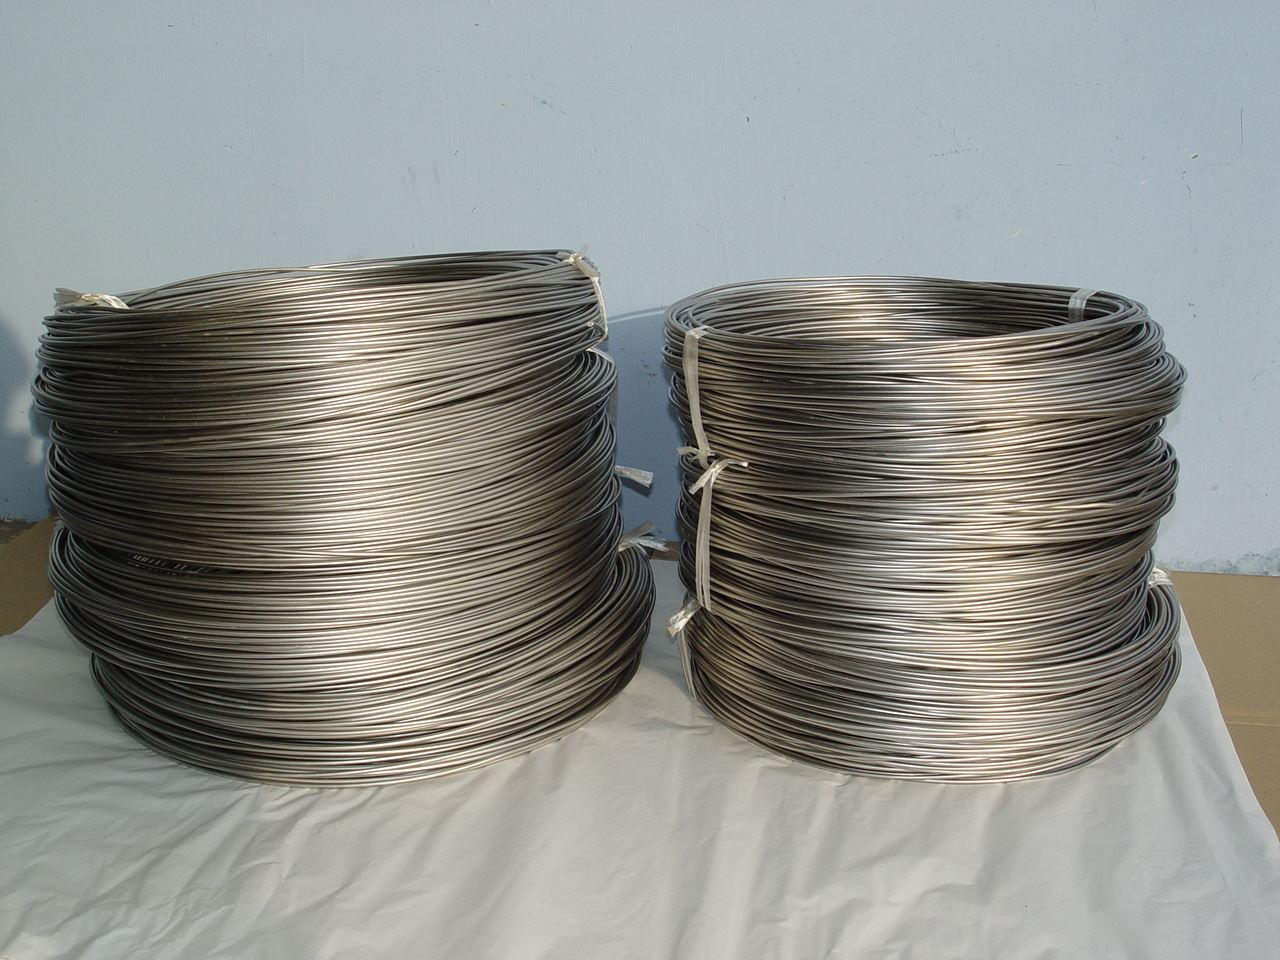
Competition in the titanium alloy industry:
Alcoa, Allegheny Technology Co., Ltd. (ATI), American Precision Casting Company and Russia's VSMPO-AVISMA Company and Chinese titanium companies together account for 50% to 60% of the titanium market share. Russia's VSMPO-AVISMA is the largest supplier of rolled products in the aviation sector. At present, only four countries in the world, the United States, Russia, Japan and China, have mastered the complete titanium industrial production technology. The output of ordinary titanium materials in my country ranks first in the world, and there is a serious overcapacity of low- and medium-yield titanium materials and insufficient supply of high-end materials. Domestic high-end titanium alloy materials are also in short supply and rely on imports for a long time.
Risk Analysis:
The supply of low-end titanium products in the market is sufficient, the gross profit margin is likely to decline, the technical research on high-end titanium alloy materials is less than expected, and domestic substitution is less than expected.